← All deputies

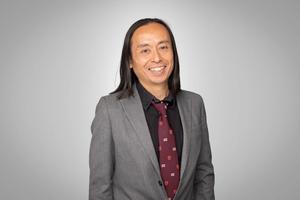
David Goy

Sitting this term since July 2025

Email
david.goy@deputies.gov.gg
As listed on the States of Guernsey register
Manifesto rating43 / 100 · Needs a second draftHow scored
David Goy

David Goy stood on a platform centred on economic independence, tax justice, and long-term resilience for Guernsey. His manifesto emphasised reducing the island's reliance on the UK and EU across trade, energy, and food supply, while ensuring that fiscal burdens fall on those best placed to bear them.

Among his most significant pledges, Goy proposed establishing independent Guernsey trade offices overseas to diversify import sources beyond existing partners, and extending the airport runway to attract cargo flights, new international routes, and logistics companies. On food and energy security, he committed to subsidising vertical farming and aquaculture alongside a strategic food reserve, and to investing in tidal energy given the island's exceptional tidal currents.

On taxation, Goy argued that GST should not be considered until wealthier residents contribute more, and proposed a Fair Share Tax targeting undisclosed income from entities with Guernsey property ties and trust distributions to high-net-worth beneficiaries, while exempting pensions and legitimate inheritances. He also pledged a monthly levy on properties left vacant for more than six months, with revenue directed toward affordable housing. Foreign policy decisions, he argued, should require a full States debate before commitment.


17

Amendments tabled

84%

States participation

337

States votes

0

Committee seats

Committee workload

David Goy holds no seat on any States committee, authority or board, so has no committee meetings to attend. Read the attendance figures below with that in mind: they cover the States chamber only.

Seats as listed on parliament.gg, checked 16 October 2026.

Voted or took a side on 84% of 337 recorded votes on propositions and amendments in the States chamber since the start of this States term — procedural motions count alongside substantive policy votes, and abstaining or being absent both count against the rate — frequently absent or abstaining. Committee meetings are counted separately, below.

Have your say

Discussion

Readers' comments. Not David Goy’s own response.

Discussion

Read what other readers make of Goy’s record, or add your own view.

Comments run on Disqus, a separate service. Opening them loads Disqus, which sets its own cookies. See the Disqus privacy policy.

Manifesto

Promises, and how they voted

3 of 9 promises kept on States votes, none broken. Of the 6 with no testing vote, 6 are rated outstanding on the public record.

One row per policy area. Open an area to see each promise, the recorded States votes that test it and whether this deputy voted to deliver. Where no recorded vote bears on a promise, an AI delivery verdict assesses progress against the public record.

Kept / voted to deliverBroken / voted againstNo recorded vote yetAbsent or abstained
Housing & Planning1 of 1 kept · 1 vote
  • Keptspecific

    Candidate will introduce a monthly levy on properties vacant for more than six months to fund affordable housing.

    “Vacant Property Levy: Monthly levy on homes vacant >6 months: Revenue funds affordable housing. Encourage ultra-rich to sell/rent at prices islanders can afford. Renovations and inheritances exempt.”

    HousingTax And Gst

    1 recorded vote tests this promise

    1 Pour
    • 02 Oct 2026✓Amendment 42 — Pour, voted to deliver10-26Lost

      Motion put to the States: To insert an additional proposition as follows: “To direct the Policy & Resources Committee to investigate the financial yield and legal framework required to implement an Underutilised Property Levy (UPL) applying to underutilised residential and commercial property, based on: (a) residential property being treated as underutilised where it is used as a secondary or holiday home for fewer than 183 days per calendar year, or remains substantially vacant and unused for more than 12 months, subject to defined exemptions; (b)commercial property being treated as underutilised where it remains vacant, unleased or non-operational for more than 12 months, subject to defined exemptions; and (c) liability being calculated by applying a policy-determined multiplier to the property's existing Tax on Real Property (TRP) assessment; with the detailed framework, including exemptions, ant-avoidance safeguards, administrative and enforcement arrangements, and transitional provisions, to be developed in accordance with the details outlined in the Explanatory note; and to lay a comprehensive report before the States of Deliberation no later than June 2027 detailing the financial yield, legislative framework and enforcement mechanisms required for its operation.”

      Voting Pour delivers this

      Amendment 42 directs investigation of an Underutilised Property Levy on empty residential and commercial property. This is close to the vacant-property levy promised, though it is an investigation and not specifically a monthly levy funding affordable housing.

      Official voting record →

Economy, Tax & Cost of Living2 of 5 kept · 15 votesNo vote yet: 3 not yet tested
  • Keptconditional

    Candidate will oppose GST until wealthy individuals pay their fair share of tax.

    “GST should not even be a consideration until the wealthiest pay their fair share.”

    Tax And GstPublic Finances

    12 recorded votes test this promise

    7 Pour · 4 Contre · 1 away
    • 02 Oct 2026✓Tax Reform 2026 Prop 1 (amended by A16 & A52 & A55 & A58) — Contre, voted to deliver22-17Carried

      Motion put to the States: Whether, after consideration of the Policy Letter ''Tax Reform 2026'' dated 8 June 2026, they are of the opinion: 1. To direct the Policy & Resources Committee to implement the package of tax reforms to make Guernsey and Alderney more financially sustainable as set out in sections 9 and 10 with the rates and thresholds as described in Appendix 7, save that, in relation to GST, food produced or grown by small independent suppliers is to be taxed at a rate of 0% and not at 3%, and with the following clarifications, and subject to the following: A) the Policy & Resources Committee, working with the Committee for Employment & Social Security, shall not bring GST into operation unless: i. the associated personal income tax and social security contribution mitigations are in force and operational, and are being applied through the relevant deduction, collection and assessment arrangements, before GST becomes chargeable; ii. the approved GST-related increases in the States Pension, income support and other benefits have taken effect, with payments at the increased rates commencing before GST becomes chargeable; and iii. the Essential Costs Relief Payment arrangements are in force and operational; for the purpose of this Proposition, an intention to apply relief retrospectively, make compensatory payments later or complete the necessary systems after GST has commenced shall not constitute implementation of the Mitigation Measures; b) the Policy & Resources Committee: i. shall defer the commencement of GST where any of the conditions in this Proposition 1(a) cannot be met; ii. shall revise the implementation timetable so that those conditions are met, including any necessary alignment with the commencement of a tax or contribution year; and iii. shall report promptly to the States on the reason for the delay, its financial implications and the revised timetable; c) no authority otherwise given under this item shall permit GST to commence in advance of compliance with those conditions; d) the Policy & Resources Committee and the Committee for Employment & Social Security, before any instrument bringing GST into operation is made or submitted for approval, shall publish a joint implementation assurance report: i. identifying each Mitigation Measure, its commencement date and the date from which its financial effect will be delivered; ii. setting out the evidence that the necessary legislation, staffing, systems, payroll interfaces, assessment arrangements and payment processes are ready to deliver the measures in accordance with this Proposition; and iii. identifying any outstanding implementation risks and explaining how those risks have been addressed, including the arrangements for receiving and determining Essential Costs Relief Payment Claims; e) where compliance depends upon an event occurring after publication of that report, the Committees shall publish confirmation that the event has occurred before GST becomes chargeable, if the conditions cannot be met, the terms under this proposition at 1(b) shall apply notwithstanding any commencement date previously appointed; f) the legislation implementing GST shall give effect to these commencement conditions and shall not confer power to dispense with them by administrative decision; and

      Voting Contre delivers this

      This is the main Tax Reform proposition implementing the package including GST. Voting Contre opposes GST, as the promise commits.

      Official voting record →

    • 02 Oct 2026✓Tax Reform 2026 Prop 1A (as inserted by A55) — Contre, voted to deliver20-19Carried

      Motion put to the States: 1A To agree, notwithstanding Proposition 1, the following: i. to implement the package of tax reforms to make Guernsey and Alderney more financially sustainable as set out in sections 9 and 10 with the rates and thresholds as described in Appendix 7 in the first year of implementation SUBJECT TO the rates and thresholds progressing as follows: with effect from 24 months following the implementation of changes to Income Tax and Social Security contributions and the introduction of a GST: o Social Security contributions allowance: £12,600 (provisional*); o Higher rate of Income Tax threshold: £30,500 (provisional*); o Pre-emptive increase in pensions and other benefits: 0.6%; o Essentials Costs Relief Payment: set to reflect the estimated impact of a 4% GST on a basket of essential goods as described in Billet d’État No III of 2026; o GST: 4%; and, with effect from 48 months following the implementation of changes to Income Tax and Social Security contributions and the introduction of a GST: o Social Security contributions allowance: £13,000 (provisional*); o Higher rate of Income Tax threshold: £33,000 (provisional); o Pre-emptive increase in pensions and other benefits: 0.6%; o Essential Costs Relief Payment: set to reflect the estimated impact of a 5% GST on a basket of essential goods as described in Billet d’État No III of 2026; o GST: 5%. *monetary thresholds to be adjusted for inflation prior to implementation ii. with the Committee for Employment & Social Security to recommend to the States of Deliberation annually uprating: o the personal Income Tax allowance; o the Social Security contributions allowance; o the Higher Rate of Income Tax threshold; o the Essentials Cost Relief Payment; and o the rates of the States Pension, Income Support and any other impacted benefits by a minimum of RPIX to ensure that the real value after inflation of the protection incorporated in the package of reform is maintained.”. iii. to include within the Fiscal Policy Framework a fiscal rule that GST shall not exceed 5%.

      Voting Contre delivers this

      Proposition 1A implements the tax reform package including GST. Voting Contre opposes it, though the proposition adds conditions and safeguards.

      Official voting record →

    • 01 Oct 2026✓Amendment 28 — Pour, voted to deliver9-27Lost

      Motion put to the States: To insert an additional proposition as follows@ ''To direct the inclusion within the scope of longer-term work envisaged in Appendix 3 of the Tax Review Sub-Committee's report, an examination of wealth and asset-based taxation measures as potential revenue-raising tools, including consideration of their potential contribution to fiscal sustainability, tax equity and the broadening of the Bailiwick's tax base, and the extent to which sure measures could be implemented without materially undermining the competitiveness of Guernsey's economy, including its financial services sector, or its ability to attract investment and economically active residents. Such work shall include the commissioning of independent analysis to understand and quantify the net economic and fiscal contribution made by High-Net-Worth residents and associated relocation programmes.''.

      Voting Pour delivers this

      This tests the condition of the promise by examining wealth and asset-based taxation, which would make the wealthy pay more before or alongside GST.

      Official voting record →

    • 01 Oct 2026✓Amendment 55 — Contre, voted to deliver21-16Carried

      Motion put to the States: 1. To substitute in Proposition 1 the word “and” for the full stop and to insert, immediately after Proposition 1, the following additional Proposition: “1A To agree, notwithstanding Proposition 1, the following: i. to implement the package of tax reforms to make Guernsey and Alderney more financially sustainable as set out in sections 9 and 10 with the rates and thresholds as described in Appendix 7 in the first year of implementation SUBJECT TO the rates and thresholds progressing as follows: with effect from 24 months following the implementation of changes to Income Tax and Social Security contributions and the introduction of a GST: o Social Security contributions allowance: £12,600 (provisional*); o Higher rate of Income Tax threshold: £30,500 (provisional*); o Pre-emptive increase in pensions and other benefits: 0.6%; o Essentials Costs Relief Payment: set to reflect the estimated impact of a 4% GST on a basket of essential goods as described in Billet d’État No III of 2026; o GST: 4%; and, with effect from 48 months following the implementation of changes to Income Tax and Social Security contributions and the introduction of a GST: o Social Security contributions allowance: £13,000 (provisional*); o Higher rate of Income Tax threshold: £33,000 (provisional); o Pre-emptive increase in pensions and other benefits: 0.6%; o Essential Costs Relief Payment: set to reflect the estimated impact of a 5% GST on a basket of essential goods as described in Billet d’État No III of 2026; o GST: 5%. *monetary thresholds to be adjusted for inflation prior to implementation ii. with the Committee for Employment & Social Security to recommend to the States of Deliberation annually uprating: o the personal Income Tax allowance; o the Social Security contributions allowance; o the Higher Rate of Income Tax threshold; o the Essentials Cost Relief Payment; and o the rates of the States Pension, Income Support and any other impacted benefits by a minimum of RPIX to ensure that the real value after inflation of the protection incorporated in the package of reform is maintained.”. iii. to include within the Fiscal Policy Framework a fiscal rule that GST shall not exceed 5%. 2. To delete Proposition 3 and replace it with: “To direct that before any increase in the rate of GST from 3% to 4%, or from 4% to 5% shall take effect, the Policy & Resources Committee shall publish an assurance review from the independent Fiscal Policy Panel affirming that in the Panel’s opinion the increase is consistent with the Fiscal Policy Framework and is necessary and appropriate having regard to the island’s fiscal, economic and inflationary environment and the impact of economic conditions and the proposed increase on lower- and middle income households. In the event that the Fiscal Policy Panel’s assurance review concludes that the scheduled increase in the rate of GST does not satisfy the requirements herein, the scheduled increase shall not take effect and shall instead be deferred for at least 12 months until the Panel concludes that the requirements have been met.”. 3. In Proposition 4, to insert after the words “to give effect to the above decisions” the following: “, and to direct that such legislation include provision requiring that any resolution to approve legislation that seeks to vary or repeal the legislative protections referred to in paragraph 10.4, and outlined in Resolution I. 2 of Billet d’État No III of 2026 made on the 26th February 2026, shall be deemed to have carried only if not less than two-thirds of the Members present vote in favour.”. 4. To insert an additional Proposition: “To direct the Policy & Resources Committee to take all such steps as are necessary to ensure that the States are provided with the opportunity to consider in the 2028 Budget Report options for an additional lifetime tax allowance (an Additional Earnings Allowance) in respect of otherwise taxable earned income to incentivise younger earners to remain, return or establish in the island.”. 5. To insert an additional Proposition: “To direct the Policy & Resources Committee and the Committee for Housing to take all such steps as are necessary to ensure that the States are provided with the opportunity to consider in the 2028 Budget Report options to introduce a tax-free Guernsey Property Savings Account (GPSA) to incentivise and better enable saving by first-time buyers for the purposes of buying a home in Guernsey or Alderney.”. 6. To insert an additional Proposition: “To direct the inclusion within the scope of longer-term work (envisaged in Appendix 3 of the Tax Review Sub-committee’s report) an examination of the role of Social Security contributions in Guernsey’s revenue base.”. 7. To replace the additional proposition to be inserted by Amendment 24 with the following: “To direct the Policy & Resources Committee, in consultation with the Committee for Employment & Social Security, as part of the Government Work Plan Super Priority ‘Shape and Strengthen the Focus on Early Years and Families,’ to consider the re-introduction of child tax allowances or credits, alternative tax or Social Security measures, and existing measures including, but not limited to, Family Allowance, charge of child and dependent relative tax provisions, reporting as soon as practical to the States of Deliberation with recommendations which should include costed, targeted measures that most effectively support families with the costs of raising children.”.

      Voting Contre delivers this

      Amendment 55 inserts the proposition to implement the GST tax reform package with conditions attached. Voting Contre works against GST going ahead.

      Official voting record →

    • 30 Sept 2026✓Amendment 45 — Pour, voted to deliver18-21Lost

      Motion put to the States: To substitute in Proposition 1 the word “and” for the full stop and to insert, immediately after Proposition 1, the following additional Proposition: “1A. To direct, notwithstanding Proposition 1, the Policy & Resources Committee: a) not to continue with “the Reserved Measures”, so defined as: i. the introduction of a goods and services tax (“GST”) ii. the proposed International Services Entity arrangements insofar as those arrangements are dependent upon, or form part of, the introduction of GST; and iii. any reductions or restructuring of personal income tax, any associated payments, allowances or mitigations, which are intended to offset or redistribute the effects of GST; b) to continue with the development and implementation of the remainder of the tax reform package provided those measures are capable of proceeding independently of the Reserved Measures; c) to report to the States by October 2027 with regard to: i. the receipts from Pillar Two arrangements and the best available estimate of the recurring annual revenues arising from them; ii. recurring expenditure reductions and efficiencies which have been implemented, including but not limited to progress against the approximate £20 million assumption incorporated within the financial forecasts; iii. an updated assessment of the States’ financial position, including the General Revenue Reserve, investment performance, infrastructure requirements, financing commitments and debt-repayment obligations; iv. updated demographic, workforce and public service demand projections; v. progress in addressing the outstanding operational, staffing, systems and administrative issues within the Revenue Services, together with an assessment of its readiness to implement and administer any additional taxes; vi. updated implementation and administration costs associated with the Reserved Measures, including expenditure already incurred and any avoidable, unavoidable or abortive costs; and that the original propositions of this report shall not seek approval for the Reserved Measures; d) put not before the States any proposals in relations to the Reserved Measures until after the report outlined in 1A(c) has been considered by the States.”.

      Voting Pour delivers this

      Amendment 45 would stop work on the 'Reserved Measures', which appear to include GST. Voting Pour stops the GST work.

      Official voting record →

    • 30 Sept 2026✓Amendment 54 — Pour, voted to deliver13-27Lost

      Motion put to the States: To delete all propositions and insert: 1. To agree that consideration of the proposed Goods and Services Tax and the associated Income Tax and Social Security contribution reforms detailed in the Policy Letter shall be deferred until a further review of revenue-generation options has been conducted. 2. To direct the Policy & Resources Committee to investigate the introduction of a tax on insurance premiums. 3. To direct the Policy & Resources Committee to return to the States no later than March 2027 with its findings and proposals for the introduction of a tax on insurance premiums, alongside and as an alternative to the proposals for GST detailed in this Policy Letter.

      Voting Pour delivers this

      The amendment defers GST until a further review of revenue-generation options has been done. That is the closest available test of GST not being considered until other, fairer revenue sources are examined.

      Official voting record →

    • 30 Sept 2026·Amendment 48 — Contre, voted against, not counted as a breach5-33Lost

      Motion put to the States: In Proposition 1 after “Appendix 7” insert the following: “, subject to replacing the proposed goods and services tax with an increase in the standard rate of income tax from 20 percent to a single rate at 22 percent, which increase is to be done as soon as practicable”.

      Voting Pour delivers this

      The amendment replaces GST with a higher income tax rate, so voting Pour removes GST. It does not specifically make the wealthy pay more.

      Considered and set aside: voting this way is not clearly a breach of the promise. The promise was to oppose GST until the wealthy pay their fair share, but the motion proposed replacing GST with a 2% income tax rise for all taxpayers at a single flat rate, which is not obviously a measure targeting the wealthiest — so a deputy could reasonably vote against this specific mechanism while still honestly pursuing the underlying promise.

      Official voting record →

    • 30 Sept 2026✓Sursis Motive — Pour, voted to deliver16-24Lost

      Motion put to the States: To sursis the propositions until such time that the Chief Financial Officer has provided the States with a comprehensive report on the States financial position or 31st July 2028, whichever is earlier and to direct the Policy & Resources Committee to return the States with a tax reform package that does not include a goods and services tax.

      Voting Pour delivers this

      The sursis would send back a tax reform package that does not include GST, so voting Pour defers or avoids GST.

      Official voting record →

    • 17 Jul 2026✓Amendment 19 — Pour, voted to deliver7-30Lost

      Motion put to the States: At the end of Proposition 1 insert the words “, subject to excluding the following: “a) the introduction of a goods and services tax; b) the changes to social security contributions; c) the introduction of new, and changes to, transport taxes”.

      Voting Pour delivers this

      The amendment excludes the introduction of GST from the approved tax reform package. Voting Pour delivers opposition to GST.

      Official voting record →

    • 16 Jul 2026✓Amendment 2 — Pour, voted to deliver10-28Lost

      Motion put to the States: To delete all propositions and to substitute therefor: “1.To agree a goods and services tax shall not be introduced, and: (i) to rescind Resolution I. 1B. and Resolution I. 1C. of Billet d’Etat No. XIX dated 14th October, 2024 made on 8th November 2024; and (ii) to direct the Policy & Resources Committee to cease all preparations for the introduction of any goods and services tax.”.

      Voting Pour delivers this

      The amendment states that GST shall not be introduced and rescinds the earlier GST resolutions. Voting Pour delivers the promise.

      Official voting record →

    • 16 Jul 2026✓Amendment 14 — Pour, voted to deliver15-23Lost

      Motion put to the States: To delete Propositions 1 to 3 and substitute therefor: “1.To agree that neither the proposed Goods and Services Tax nor the associated Income Tax and Social Security contribution reforms detailed in the Policy Letter shall be introduced as part of the Tax Reform Programme. 2.To agree that the proposed Transport Taxes shall proceed as set out in this Policy Letter at Paragraph 9.7 and as more specifically described therein. 3.To agree that the proposed Corporate Tax amendments shall proceed as set out in Paragraph 9.21 of this Policy Letter and as more specifically described therein, excepting that at the third bullet point of paragraph 9.21, the term “ISE” shall be substituted with “Corporate Levy” (and this substitution shall take effect wherever relevant). 4.To direct the Policy & Resources Committee to develop and bring before the States proposals, for implementation on the same timetable as the tax measures proposed in this Policy Letter where reasonably practicable, for the introduction of a Corporate Levy payable by registered Guernsey companies, having regard to the work previously undertaken by the Tax Review Sub-Committee, and including consideration of whether such levy should comprise: a fixed annual levy payable by each registered company; a levy differentiated according to the size or scale of the undertaking, including consideration of whether existing company classifications may provide an appropriate and proportionate basis for differentiation; or such other structure as the Committee considers best achieves the objectives of fairness, administrative simplicity and efficient revenue collection. 5.To direct the Committee for Economic Development, in consultation with the Policy & Resources Committee, to develop and bring before the States, on the same timetable where reasonably practicable, proposals for the introduction of a Visitor Levy in accordance with the extant States Resolution, with all revenues arising from such levy to be paid into the General Revenue Account and not hypothecated for expenditure by any particular Committee or industry sector. 6.To direct the Policy & Resources Committee to revise the implementation programme and associated implementation budget for Tax Reform to reflect the removal of the proposed Goods and Services Tax and associated Income Tax and Social Security contribution reforms, including the consequential reduction in implementation cost, implementation activity, systems development, staffing and administrative requirements. 7. To direct the Policy & Resources Committee to return to the States with: 1. a revised implementation programme; 2. a revised implementation budget; 3. revised estimates of one-off implementation costs; 4. revised estimates of ongoing administration costs; 5. revised estimates of annual recurring revenues; and 6. revised staffing assumptions, reflecting the alternative package approved under this Proposition within a period that results in the States being capable of meeting the proposed implementation timetable as proposed within the Policy Letter. 8.To direct the Policy & Resources Committee to return to the States with an assurance review in 2030 as set out in section 12 of the Policy Letter, the scope of which shall be adjusted, where necessary, to take account of the removal of GST and Social Security measures from the package under these proposals and the application of those measures considered herein.”.

      Voting Pour delivers this

      The amendment removes GST from the Tax Reform Programme. Voting Pour delivers opposition to GST.

      Official voting record →

    • 26 Feb 2026–Amendment 1 — Absent, did not take a side5-31Lost

      Motion put to the States: To delete all propositions and to substitute therefor: “1. To agree a goods and services tax shall not be introduced, and: (i) to rescind Resolution I. 1B. and Resolution I. 1C. of Billet d’Etat No. XIX dated 14th October, 2024 made on 8th November 2024; and (ii) to direct the Policy & Resources Committee to cease all preparations for the introduction of any goods and services tax.”. View this proposition's information page on gov.gg

      Voting Pour delivers this

      The amendment would rule out introducing GST and rescind the earlier GST resolutions. Voting Pour delivers opposition to GST.

      Official voting record →

    Related votes (shown for context; too partial or indirect to count towards the score)

    • 02 Oct 2026·Amendment 35 — Pour5-32Lost

      Motion put to the States: To insert an additional proposition as follows: "To direct the Policy & Resources Committees to investigate the financial yield and legal framework required to implement a Fair Contribution Levy (FCL) for households occupying residential properties within the top 10% of Tax on Real Property (TRP) values, establishing a minimum combined contribution of income tax and Social Security based on the combined contribution of a median resident household and scaled according to the property's TRP value relative to the median residential TRP value, with further details of the proposed framework set out in the Explanatory note; and to lay a comprehensive report before the States of Deliberation no later than June 2027 detailing the legislative, administrative and enforcement mechanisms required for its operation."

      The investigation of a levy on the wealthiest households bears on the condition that the wealthy pay a fair share before GST. It is an investigation only.

      Official voting record →

    • 02 Oct 2026·Amendment 36 — Pour3-29Lost

      Motion put to the States: To insert an additional proposition as follows: "To direct the Policy & Resources Committee to investigate the financial yield and legal framework required to implement a High-Net-Worth Residency Scheme (HNWRS) for new high-net-worth individuals who, on or after 1 January 2028, use an Open Market (Part A) property as the basis for taking up their own residency in Guernsey, with eligibility based on a minimum global net worth of £5 million, excluding the primary residence, or sustainable annual global income of £750,000; requiring qualifying participants to make a minimum annual personal income tax contribution of £150,000 and the applicable Social Security contribution; and to lay a comprehensive report before the States of Deliberation no later than June 2027 detailing the legislative, administrative and enforcement mechanisms required for its operation, including the maters set out in the Explanatory note."

      The investigation of a high-net-worth residency scheme bears on the condition that the wealthy contribute fairly. It is an investigation only.

      Official voting record →

    • 01 Oct 2026·Amendment 52 — Pour33-4Carried

      Motion put to the States: To insert, in Proposition 1 immediately after the words “Appendix 7” the following: “Subject to the following: a) the Policy & Resources Committee, working with the Committee for Employment & Social Security, shall not to bring GST into operation unless: i. the associated personal income tax and social security contribution mitigations are in force and operational, and are being applied through the relevant deduction, collection and assessment arrangements, before GST becomes chargeable; ii. the approved GST-related increases in the States Pension, income support and other benefits have taken effect, with payments at the increased rates commencing before GST becomes chargeable; and iii. the Essential Costs Relief Payment arrangements are in force and operational. for the purposes of this Proposition, an intention to apply relief retrospectively, make compensatory payments later or complete the necessary systems after GST has commenced shall not constitute implementation of the Mitigation Measures. b) the Policy & Resources Committee: i. shall defer the commencement of GST where any of the conditions in this Proposition 1(a) cannot be met; ii. shall revise the implementation timetable so that those conditions are met, including any necessary alignment with the commencement of a tax or contribution year; and iii. shall report promptly to the States on the reason for the delay, its financial implications and the revised timetable. c) no authority otherwise given under this item shall permit GST to commence in advance of compliance with those conditions. d) the Policy & Resources Committee and the Committee for Employment & Social Security, before any instrument bringing GST into operation is made or submitted for approval, shall publish a joint implementation assurance report: i. identifying each Mitigation Measure, its commencement date and the date from which its financial effect will be delivered; ii. setting out the evidence that the necessary legislation, staffing, systems, payroll interfaces, assessment arrangements and payment processes are ready to deliver the measures in accordance with this Proposition; and iii. identifying any outstanding implementation risks and explaining how those risks have been addressed, including the arrangements for receiving and determining Essential Costs Relief Payment claims. e) where compliance depends upon an event occurring after publication of that report, the Committees shall publish confirmation that the event has occurred before GST becomes chargeable. If the conditions cannot be met, the terms under this Proposition at 1(b) shall apply notwithstanding any commencement date previously appointed. f) the legislation implementing GST shall give effect to these commencement conditions and shall not confer power to dispense with them by administrative decision.”.

      The conditions on bringing GST into operation are a safeguard within the GST package and are only loosely connected to the promise.

      Official voting record →

    • 30 Sept 2026·Amendment 57 — Pour10-27Lost

      Motion put to the States: To delete the propositions and substitute therefor: “1. To direct the States Assembly and Constitution Committee to return to the States at its meeting on 17th March 2027 with arrangements for the holding (under the provisions of the relevant legislation) of a referendum on Tax reform. 2. To direct the Committee to agree that the question to be put to the electorate in the referendum shall be in a binary form along the following lines: “Do you support the introduction of the tax reform package proposed by the Policy & Resources Committee? Yes or No.”.”.

      Holding a referendum on tax reform could delay or block GST, but it tests public consent, which is not the promise's actual condition.

      Official voting record →

    • 15 Jul 2026·Amendment 3 — Pour14-25Lost

      Motion put to the States: To delete the propositions and substitute therefor: 1. To direct the States Assembly and Constitution Committee to return to the States at its meeting on 21st October 2026 with arrangements for the holding (under the provisions of the relevant legislation) of a referendum on Tax reform. 2. To direct the Committee to agree that the question to be put to the electorate in the referendum shall be in a binary form along the following lines: “Do you support the introduction of a GST (goods and services tax)? Yes or No.”.

      Holding a referendum on tax reform could delay or block GST, but it tests public consent, which is not the promise's actual condition.

      Official voting record →

    • 26 Feb 2026·Proposition 1d-f — Absent32-2Carried

      Motion put to the States: AND (IRRESPECTIVE OF THE STATES’ DECISION ON PROPOSITIONS 1b OR 1c) d. supplies sold by registered charities should be exempt from the Goods and Services Tax and that provision should be made to allow registered charities to reclaim the Goods and Services Tax incurred on supplies purchased as outlined in section 8; AND e. the proposed International Services Entity scheme should incorporate international insurance services and e-gaming activities; AND f. The application of all other exempt and zero-rated supplies should be as outlined in Section 8.

      The charity exemption is a design detail inside the GST package and is not a real test of the promise.

      Official voting record →

    • 26 Feb 2026·Proposition 1b — Absent24-12Carried

      Motion put to the States: b. (i) the Goods & Services Tax should be applied at a standard rate of 5%, andthat all foodstuffs should be subject to the tax at the standard rate; AND (ii)an Essentials Cost Relief Payment scheme should be implemented as outlined in Section 4, with the fixed payment set provisionally (subject to review as set out below) at £520 a year for a single adult or £860 a year for a couple, reflecting the estimated annual GST incurred by a household on Income Support; and that the responsibility and administering of this payment should be added to the mandate of the Committee for Employment & Social Security; and that the payment should be increased each January in line with Income Support rates, the value of the payment being fully reviewed in line with the minimum income standard whenever that exercise is repeated;

      This motion adopts GST at a 5% standard rate, including on food. Voting Contre keeps GST off the table, as the promise requires.

      Deputy’s response: The substantive debate on GST took place during the July 2026 Tax Reform debate, where I lodged four amendments as alternatives to GST: an Underutilised Property Levy, a Fair Contribution Levy, a Premium Road Levy, and a High-Value Document Duty. Motions claiming they were out of scope were brought forward to prevent them from being debated. The motions succeeded and so none of them were debated. - Deputy David Goy

      Official voting record →

  • Keptspecific

    Candidate will introduce a Fair Share Tax targeting high-net-worth individuals with Guernsey property ties.

    “Fair Share Tax: Tax justice act to target: 'Stealth income' from entities with Guernsey property ties. Trust distributions to HNWI beneficiaries with local properties. Legitimate inheritances and pensions exempt.”

    Tax And GstPublic Finances

    3 recorded votes test this promise

    3 Pour
    • 02 Oct 2026✓Amendment 35 — Pour, voted to deliver5-32Lost

      Motion put to the States: To insert an additional proposition as follows: "To direct the Policy & Resources Committees to investigate the financial yield and legal framework required to implement a Fair Contribution Levy (FCL) for households occupying residential properties within the top 10% of Tax on Real Property (TRP) values, establishing a minimum combined contribution of income tax and Social Security based on the combined contribution of a median resident household and scaled according to the property's TRP value relative to the median residential TRP value, with further details of the proposed framework set out in the Explanatory note; and to lay a comprehensive report before the States of Deliberation no later than June 2027 detailing the legislative, administrative and enforcement mechanisms required for its operation."

      Voting Pour delivers this

      Amendment 35 directs investigation of a Fair Contribution Levy on households in the top 10% of property values, a wealth-targeted property-linked levy in the spirit of a Fair Share Tax. It is investigative only.

      Official voting record →

    • 02 Oct 2026✓Amendment 36 — Pour, voted to deliver3-29Lost

      Motion put to the States: To insert an additional proposition as follows: "To direct the Policy & Resources Committee to investigate the financial yield and legal framework required to implement a High-Net-Worth Residency Scheme (HNWRS) for new high-net-worth individuals who, on or after 1 January 2028, use an Open Market (Part A) property as the basis for taking up their own residency in Guernsey, with eligibility based on a minimum global net worth of £5 million, excluding the primary residence, or sustainable annual global income of £750,000; requiring qualifying participants to make a minimum annual personal income tax contribution of £150,000 and the applicable Social Security contribution; and to lay a comprehensive report before the States of Deliberation no later than June 2027 detailing the legislative, administrative and enforcement mechanisms required for its operation, including the maters set out in the Explanatory note."

      Voting Pour delivers this

      Amendment 36 directs investigation of a High-Net-Worth Residency Scheme tied to Open Market property use, which is close to a tax on wealthy individuals with Guernsey property ties. It only asks for investigation, so it falls short of introducing the tax.

      Official voting record →

    • 01 Oct 2026✓Amendment 28 — Pour, voted to deliver9-27Lost

      Motion put to the States: To insert an additional proposition as follows@ ''To direct the inclusion within the scope of longer-term work envisaged in Appendix 3 of the Tax Review Sub-Committee's report, an examination of wealth and asset-based taxation measures as potential revenue-raising tools, including consideration of their potential contribution to fiscal sustainability, tax equity and the broadening of the Bailiwick's tax base, and the extent to which sure measures could be implemented without materially undermining the competitiveness of Guernsey's economy, including its financial services sector, or its ability to attract investment and economically active residents. Such work shall include the commissioning of independent analysis to understand and quantify the net economic and fiscal contribution made by High-Net-Worth residents and associated relocation programmes.''.

      Voting Pour delivers this

      Amendment 28 would add examination of wealth and asset-based taxation to the longer-term tax work, which supports taxing the wealthy more. It is a study commitment, not a levy.

      Official voting record →

    Related votes (shown for context; too partial or indirect to count towards the score)

    • 02 Oct 2026·Amendment 37 — Pour8-28Lost

      Motion put to the States: To insert an additional proposition as follows: "To direct the Policy & Resources Committee to investigate the financial yield, legal framework and implementation mechanisms required to introduce a High-Value Document Duty (HVDD) on residential property transactions exceeding £2.5 million, structured on a marginal basis whereby progressive surcharges apply only to the portion of standard Document Duty attributable to each applicable property-value band, based on the framework set out in the Explanatory note, including the recommended surcharge rates of 25%, 50% and 75% as starting-point values; and to lay a comprehensive report before the States of Deliberation no later than June 2027 detailing the legislative, administrative and enforcement mechanisms required for its operation."

      Amendment 37 directs investigation of a high-value document duty on residential property over £2.5m. This is a partial, indirect wealth-targeted property measure.

      Official voting record →

    • 02 Oct 2026·Amendment 43 — Pour29-7Carried

      Motion put to the States: To insert an additional proposition as follows: “To agree in principle that a new Proportional Property Tax (PPT), based on property value, and Land Value Tax (LVT) based on the unimproved value of a parcel of land, should be investigated and to direct the Policy & Resources Committee to return to the States no later than June 2028 with proposals which should include consideration of: a) How property tax should be calculated and applied and whether there should be any exemptions; b) Whether a new tax should be applied in addition to or instead of Domestic Tax on Real Property; c) A mechanism to allow pensioners and low-income households to defer the payment of property taxes until the sale or the transfer of the property to a new owner; d) The potential to partly or fully replace Document Duty or for specified categories of property purchase, including: i) first-time buyers only, or ii) purchases of principal private residences only, or iii) for all residential purchases. e) The potential to partly fund an increase to the scale of the amount of interest paid that is allowable for Mortgage Income Tax Relief for Income Tax; f) A premium rate of Proportional Property Tax for second homes, unoccupied homes, and properties in foreign ownership; g) A banded or tiered mechanism to allow lower rates for residences at lower values.".

      Amendment 43 agrees in principle to investigate a property-value tax and a land value tax, which would fall more heavily on wealthy property owners. It is broad and not targeted at high-net-worth individuals specifically.

      Official voting record →

    • 02 Oct 2026·Tax Reform 2026 Prop 12 (inserted by A43) — Pour22-13Carried

      Motion put to the States: To agree in principle that a new Proportional Property Tax (PPT), based on property value, and Land Value Tax (LVT) based on the unimproved value of a parcel of land, should be investigated and to direct the Policy & Resources Committee to return to the States no later than June 2028 with proposals which should include consideration of: a) How property tax should be calculated and applied and whether there should be any exemptions; b) Whether a new tax should be applied in addition to or instead of Domestic Tax on Real Property; c) A mechanism to allow pensioners and low-income households to defer the payment of property taxes until the sale or the transfer of the property to a new owner; d) The potential to partly or fully replace Document Duty or for specified categories of property purchase, including: i) first-time buyers only, or ii) purchases of principal private residences only, or iii) for all residential purchases. e) The potential to partly fund an increase to the scale of the amount of interest paid that is allowable for Mortgage Income Tax Relief for Income Tax; f) A premium rate of Proportional Property Tax for second homes, unoccupied homes, and properties in foreign ownership; g) A banded or tiered mechanism to allow lower rates for residences at lower values. (Inserted by A43)

      The carried proposition on investigating a property-value tax and land value tax is a broad property-wealth measure only loosely connected to a Fair Share Tax.

      Official voting record →

  • No recorded votedirectional

    Candidate will subsidise vertical farming and aquaculture and establish a strategic food reserve.

    “Food Security: Subsidise vertical farms, aquaculture and fishing. Incentivise local food production. Strategic food reserve.”

    Agriculture And FishingInfrastructure And Transport
    No recorded vote - delivery verdictNot yet testedhigh confidence

    Since taking office in July 2025, Deputy Goy has lodged no proposition, question, or amendment specifically relating to subsidies for vertical farming, aquaculture, or the establishment of a strategic food reserve. His parliamentary activity has focused primarily on tax reform (his 'Productivity Incentivisation Tax' plan) and AI governance; an amendment he co-lodged to the January 2026 Government Work Plan (P.2025/143 Amdt 4) was lost, and no food-security workstream appears in the agreed 2026–2029 GWP. The food-security promise remains entirely at the manifesto stage with no traceable progress in States records or Guernsey press coverage.

  • No recorded votedirectional

    Candidate will establish independent Guernsey trade offices overseas to diversify import sources beyond the EU and UK.

    “Establish Guernsey Trade Offices overseas independent of UK. Diversify direct imports beyond EU/UK.”

    Economy And BusinessGovernance And Constitution
    No recorded vote - delivery verdictNot yet testedhigh confidence

    As of July 2026, no evidence was found of any States proposition, committee policy letter, or Government Work Plan workstream directed at establishing independent Guernsey trade offices overseas or formally diversifying direct imports beyond EU/UK. Deputy Goy publicly advocated for welcoming eastern investment in January 2026 (Guernsey Press, 19 Jan 2026) and his personal website continues to list trade sovereignty as a priority, but these amount to informal advocacy only. The States' 2026–2029 Government Work Plan, agreed in January 2026, identifies five 'super priorities' centred on tax reform, housing, health and harbour infrastructure, with no mention of independent overseas trade offices or import diversification from non-EU/UK sources.

  • No recorded votedirectional

    Candidate will introduce financial incentives for manufacturers, startup incubators, and R&D to diversify the economy.

    “Financial incentives for new manufacturers. Startup incubators. Research and development.”

    Economy And Business
    No recorded vote - delivery verdictNot yet testedhigh confidence

    No evidence was found of Deputy Goy having introduced, proposed, or formally advanced any policy relating to financial incentives for manufacturers, startup incubators, or R&D since taking office on 1 July 2025. His parliamentary activity has focused almost entirely on tax reform alternatives (the 'Productivity Incentivisation Tax' and GST opposition), with his Government Work Plan Amendment 4 (co-sponsored with Rob Curgenven) lost in January 2026. As of July 2026, the Guernsey Press and Bailiwick Express reported his engagement remained confined to taxation debates, with no mention of manufacturing or startup incubator initiatives.

Infrastructure & Environment0 of 2 kept · 0 votesNo vote yet: 2 not yet tested
  • No recorded votedirectional

    Candidate will pursue airport runway extension for cargo flights and new direct international routes.

    “Airport Expansion Catch Up to Jersey: Extend runway for cargo flights. Add direct routes to more countries. Attract logistics companies.”

    Infrastructure And TransportEconomy And Business
    No recorded vote - delivery verdictNot yet testedhigh confidence

    As of July 2026, Guernsey Airport's runway remained at 1,463 metres with no extension or EMAS installation underway; the previous States had left any runway decision to the States' Trading Supervisory Board tied to the next scheduled resurfacing (estimated 5–10 years away), and no new proposition, policy letter, or committee inquiry specifically linked to Deputy Goy's cargo/logistics agenda was found in the record since he took office in July 2025. Goy's own campaign website continued to list the airport's inability to handle cargo planes as an outstanding problem, and no evidence surfaced of him tabling a requête, amendment, or written question on the runway or logistics-hub issue. New passenger routes were added in 2025–26 (British Airways Heathrow from April 2026, Loganair Norwich), but these are commercially driven and unrelated to Goy's specific cargo/runway/logistics promise.

  • No recorded votedirectional

    Candidate will invest in tidal energy development and increase Guernsey's strategic energy reserves.

    “Energy Independence: Invest in tidal energy (we have one of the strongest currents in Europe). Explore alternative energy generation. Increase strategic energy reserve.”

    Environment And ClimateInfrastructure And Transport
    No recorded vote - delivery verdictNot yet testedmedium confidence

    No evidence was found of Deputy Goy initiating or advancing any proposal relating to tidal energy investment or increasing Guernsey's strategic energy reserve since taking office in July 2025. His parliamentary activity through July 2026 has been focused almost exclusively on taxation and fiscal alternatives to GST. The States-approved 2023 Electricity Strategy already assessed tidal energy and excluded it from recommended pathways on the grounds it was not yet commercially viable, and no new tidal-specific policy letter or energy reserve proposal has been attributed to Goy in any authoritative Guernsey source.

Governance & Public Services0 of 1 kept · 0 votesNo vote yet: 1 not yet tested
  • No recorded votedirectional

    Candidate will seek to opt out of harmful US/UK sanctions and require States debate before foreign policy decisions.

    “Opt out of US/UK sanctions that hurt Guernsey. Require States debate before foreign policy decisions.”

    Governance And Constitution
    No recorded vote - delivery verdictNot yet testedhigh confidence

    No proposition, amendment, committee inquiry, or policy letter by Deputy Goy relating to opting out of US/UK sanctions or requiring States debate on foreign policy decisions was found in parliamentary records or press coverage between July 2025 and July 2026. Guernsey's sanctions framework continued to automatically implement UK sanctions — including new regulations enacted in 2025 — with no challenge from Goy or any other deputy. Goy's recorded parliamentary activity focused entirely on fiscal and tax matters, with no public indication that sanctions or foreign policy governance had been advanced.

In the States

Their record in the Assembly

Took a side on 84% of 337 recorded votes and tabled 17 amendments (1 carried).

What this deputy has proposed, asked and turned up for, separate from the promise scorecard above.

Notable achievements

  1. 01

    Proposed the "Productivity Incentivisation Tax" as a full alternative to the GST-based tax reform package. Source →

  2. 02

    Had four of his five tax-reform amendments thrown out without debate, prompting cross-party criticism from other deputies as "disgraceful." Source →

  3. 03

    Got one amendment debated in the Assembly, calling it "the last chance to save Guernsey from GST" (ultimately defeated). Source →

17tabledAmendments1 carried · 10 never reached a vote · 6 other outcomes · most recent lodged 26 Oct 2026
  • 26 Oct 2026

    Amendment 12 · P.2026/82

    The Assembly never reached it, so there is no Hansard record of it being moved. Co-proposed by Tina Bury. Official filing →

    Lodged, not moved
  • 26 Oct 2026

    Amendment 24 · P.2026/82

    The Assembly never reached it, so there is no Hansard record of it being moved. Led by Aidan Matthews. Official filing →

    Lodged, not moved
  • 22 Sept 2026

    Amendment 35 · P.2026/49

    The Assembly never reached it, so there is no Hansard record of it being moved. Co-proposed by Aidan Matthews. Official filing →

    Lodged, not moved
  • 22 Sept 2026

    Amendment 36 · P.2026/49

    The Assembly never reached it, so there is no Hansard record of it being moved. Co-proposed by Garry Collins. Official filing →

    Lodged, not moved
  • 22 Sept 2026

    Amendment 37 · P.2026/49

    The Assembly never reached it, so there is no Hansard record of it being moved. Co-proposed by Aidan Matthews. Official filing →

    Lodged, not moved
  • 22 Sept 2026

    Amendment 38 · P.2026/49

    The Assembly never reached it, so there is no Hansard record of it being moved. Co-proposed by Aidan Matthews. Official filing →

    Lodged, not moved
  • 22 Sept 2026

    Amendment 39 · P.2026/49

    The Assembly never reached it, so there is no Hansard record of it being moved. Co-proposed by Aidan Matthews. Official filing →

    Lodged, not moved
  • 22 Sept 2026

    Amendment 40 · P.2026/49

    The Assembly never reached it, so there is no Hansard record of it being moved. Co-proposed by Rob Curgenven. Official filing →

    Lodged, not moved
  • 22 Sept 2026

    Amendment 41 · P.2026/49

    The Assembly never reached it, so there is no Hansard record of it being moved. Co-proposed by Aidan Matthews. Official filing →

    Lodged, not moved
  • 22 Sept 2026

    Amendment 42 · P.2026/49

    The Assembly never reached it, so there is no Hansard record of it being moved. Co-proposed by Aidan Matthews. Official filing →

    Lodged, not moved
  • 7 Jul 2026

    Amendment 17 · P.2026/49

    Rule 24(6) motion carried on a recorded vote, Pour 18, Contre 17, Ne vote pas 3, so the amendment was neither debated nor voted on. Taken on 16 Jul 2026. Co-proposed by Aidan Matthews. Official filing →

    WordingTo delete all the propositions and substitute the following:

    To delete all the propositions and substitute the following: “ To direct the Policy & Resources Committee to investigate and report on the administrative framework required to introduce an Underutilised Property Levy on long-term vacant dwellings; such a report to be laid before the States of Deliberation no later than June 2027 and to explicitly incorporate the phased 24-month transitional grace periods and statutory exemption pathways detailed in the Explanatory Note.”

    Blocked without debate
  • 7 Jul 2026

    Amendment 18 · P.2026/49

    Rule 24(6) motion carried on a recorded vote, Pour 22, Contre 15, Ne vote pas 1, so the amendment was neither debated nor voted on. Taken on 16 Jul 2026. Co-proposed by Aidan Matthews. Official filing →

    WordingTo delete all the propositions and substitute the following:

    To delete all the propositions and substitute the following: “To direct the Policy & Resources Committee to investigate the implementation of a targeted Premium Road Levy framework based on the details outlined in the Explanatory Note; and to lay a report before the States no later than June 2027 detailing the mechanisms required to collect such levies.”

    Blocked without debate
  • 7 Jul 2026

    Amendment 19 · P.2026/49

    Defeated on a recorded vote, Pour 7, Contre 30, Ne vote pas 2. Taken on 17 Jul 2026. Co-proposed by Aidan Matthews. Official filing →

    WordingAt the end of Proposition 1 insert the words “, subject to excluding the following:

    At the end of Proposition 1 insert the words “, subject to excluding the following: “a)the introduction of a goods and services tax; b)the changes to social security contributions; c)the introduction of new, and changes to, transport taxes”.

    Debated and defeated
  • 7 Jul 2026

    Amendment 20 · P.2026/49

    Rule 24(6) motion carried on a recorded vote, Pour 22, Contre 16, Ne vote pas 0, so the amendment was neither debated nor voted on. Taken on 16 Jul 2026. Co-proposed by Aidan Matthews. Official filing →

    WordingTo delete all the propositions and substitute the following:

    To delete all the propositions and substitute the following: "To direct the Policy & Resources Committee to conduct a formal fiscal impact assessment and legal review into reforming the document duty structure to introduce a tiered High-Value Document Duty multiplier framework as set out in the Explanatory Note; and to report its findings and implementation blueprints to the States of Deliberation by no later than June 2027."

    Blocked without debate
  • 7 Jul 2026

    Amendment 21 · P.2026/49

    Rule 24(6) motion carried on a recorded vote, Pour 21, Contre 16, Ne vote pas 0, so the amendment was neither debated nor voted on. Taken on 16 Jul 2026. Co-proposed by Aidan Matthews. Official filing →

    WordingTo delete all the propositions and substitute the following.

    To delete all the propositions and substitute the following. "To direct the Policy & Resources Committee to investigate the viability, financial yield, and legal framework required to implement a Fair Contribution Levy based on the principles outlined in the Explanatory Note; and to lay a comprehensive report before the States of Deliberation no later than June 2027 detailing the legislative and enforcement infrastructure required for its operation, including robust data-matching protocols utilising existing Revenue Service infrastructure."

    Blocked without debate
  • 20 Jan 2026

    Amendment 4 · P.2025/143

    Government Work Plan 2026-2029 Amendment 4

    Recorded vote: Pour 12, Contre 23, Ne vote pas 2. Taken on 29 Jan 2026. Co-proposed by Rob Curgenven. Official filing →

    WordingTo insert an additional proposition as follows:

    To insert an additional proposition as follows: “6.To direct the Policy & Resources Committee to publish progress of the Government Work Plan in a manner that is publicly available and easily accessible (for example, via a dedicated and regularly updated web page) no later than 1st July 2026 and updated at least every six months thereafter, containing clear, concrete targets, leading indicators, milestones, and both qualitative and quantitative metrics against which progress can be tracked, audited, and measured; and further, to include these specific criteria in the mid-term and end-of-term Government Work Plan reports, ensuring any significant deviations from original priorities are fully explained.”.

    Debated and defeated
  • 27 Oct 2025

    Amendment 4 · P.2025/121

    Recorded vote: Pour 23, Contre 16, Ne vote pas 1. Taken on 4 Nov 2025. Led by Aidan Matthews. Official filing →

    WordingTo delete Proposition 1 and insert a new proposition:

    To delete Proposition 1 and insert a new proposition: “1. To agree that the amount of tax relief in respect of mortgage interest paid on a principal private residence remains at its present level of £3,500 and cease the phased withdrawal of tax relief provided on mortgage interest in respect of principal private residences.”.

    Carried

A record of what this deputy proposed, not of how they voted. It does not feed the kept-rate: an amendment the Assembly never reaches never produces a vote on its substance.

84%took a sideVotes in the States337 recorded votes this term. Latest 12, all on 22 Oct 2026: 9 Pour, 2 Contre, 1 Absent
  • Open Market Housing Register (Guernsey) (Amendment) Law, 2026

    22 Oct 2026 · carried

    Absent
  • Planning Exemptions for Dower & EV Chargers

    22 Oct 2026 · carried

    Pour
  • Proposition 3

    22 Oct 2026 · carried

    Pour
  • The Extension of the UK's Contracting Party Status to the International Convention for the Conservation of Atlantic Tunas to the Bailiwick of Guernsey

    22 Oct 2026 · carried

    Pour
  • States' Register of Contact Details (Guernsey and Alderney) Law (Amendment) Ordinance, 2026

    22 Oct 2026 · carried

    Pour
  • Long-term Care Insurance (Amendment) (Guernsey) Law, 2026

    22 Oct 2026 · carried

    Pour
  • Amendment 1

    22 Oct 2026 · lost

    Pour
  • Legislative Changes to Enable Streamlining the Plan Making and Amendment Process

    22 Oct 2026 · carried

    Pour
  • Rule 26(1) Motion (* P.2026/68 (as amended A1) )

    22 Oct 2026 · lost

    Contre
  • Rule 26(1) Motion (* P.2026/67 )

    22 Oct 2026 · carried

    Contre
  • Schedule for future States' business

    22 Oct 2026 · carried

    Pour
  • Amendment 1

    22 Oct 2026 · carried

    Pour

The 12 most recent votes in the States of Deliberation’s electronic voting record, whether or not they relate to a manifesto promise.

7askedRule 14 written questions7 of 7 answered · most recent asked 06 May 2026 to Policy & Resources Committee
  • 2026-16Policy & Resources CommitteeAsked 6 May 2026

    The Productivity Incentivisation Tax (PIT) as an Alternative to GST and Corporate Tax Increases

    Answered 21 May 2026 (15 days). Question and response (PDF) →

  • 2026-1Policy & Resources CommitteeAsked 3 Dec 2025

    Senior Management Remuneration

    Answered 2 Jan 2026 (30 days). Question and response (PDF) →

  • 2025-33Policy & Resources CommitteeAsked 2 Dec 2025

    Senior Management Remuneration and Head Count

    Answered 18 Nov 2025 (-14 days). Question and response (PDF) →

  • 2025-32Policy & Resources CommitteeAsked 13 Nov 2025

    External Advice on States' Finances

    Answered 13 Nov 2025 (0 days). Question and response (PDF) →

  • 2025-29Committee for Economic DevelopmentAsked 10 Oct 2025

    Finance Consultancy Firm

    Answered 25 Oct 2025 (15 days). Question and response (PDF) →

  • 2025-28Policy & Resources CommitteeAsked 10 Oct 2025

    Consultancy Firm in respect of the SOG Tax Strategy

    Answered 23 Oct 2025 (13 days). Question and response (PDF) →

  • 2025-23Policy & Resources CommitteeAsked 25 Jul 2025

    Consultants

    Answered 15 Aug 2025 (21 days). Question and response (PDF) →

Coverage

In the news

46 Bailiwick media mentions since July 2025, peaking at 14 a month in July 2026.

Every Bailiwick media article naming this deputy, month by month. Accented bars mark coverage spikes; hover or focus any month to see the stories behind it.

Keep comparing

Deputies ranked nearby

The deputies immediately around this one on the scorecard, ranked by promises kept.

Stay up to date

David Goy’s record changes with every States sitting. Join the Facebook group or follow us on LinkedIn and we will tell you when it does.

Storyboard

What Guernsey said

Four years of public comment on local politics, in eleven events

Open the storyboard

Stay up to date

This record changes with every States sitting.

Join the Guernsey Deputy Scorecard group and we will post when a promise is tested, a verdict moves or a correction lands.

Join the Facebook groupPublic group · free · no advertising